Home Blog Page 5

Paribu’s third market in MENA after Dubai and Bahrain: CoinMENA launches in Jordan

Paribu has become the first digital asset platform to launch in Jordan under JoRegBox, the regulatory sandbox for financial technology and innovation operated by the Central Bank of Jordan.

Under the sandbox, users in Jordan can deposit Jordanian dinars into CoinMENA via CliQ, Jordan’s local instant payment system, to buy and sell crypto assets and hold them in custody on CoinMENA. This integration with local payment infrastructure allows users to access digital assets through the payment channels they already use in the country.

Third market after Bahrain and Dubai

Regulatory sandboxes allow new financial services to be offered to real users in a controlled framework under regulator oversight. CoinMENA became the first digital asset platform accepted into JoRegBox, which the Central Bank of Jordan launched in 2022 as part of its financial innovation objectives under the Economic Modernisation Vision.

Already operating under the Central Bank of Bahrain (CBB) through its CoinMENA B.S.C. entity and under the Dubai Virtual Assets Regulatory Authority (VARA) license through CoinMENA FZE, CoinMENA became the first digital asset trading platform accepted into Jordan’s sandbox, marking a milestone in its licensing process in the country. With this achievement, Jordan became the third market in the Middle East and North Africa (MENA) region that Paribu can reach through CoinMENA.

Joined Paribu through Turkey’s largest fintech acquisition

Founded in 2020 by Talal Tabbaa and Dina Sam’an, CoinMENA joined Paribu in December 2025 through what was Turkey’s largest fintech acquisition to date. Valued at up to $240 million, the deal gave Paribu direct access to MENA — one of the regions with the highest rates of digital asset adoption — through CoinMENA’s active licenses.

In recent months, CoinMENA also made headlines with a strategic partnership with Standard Chartered — which holds more than $850 billion in assets under management and carries Global Systemically Important Bank (G-SIB) status as designated by the Financial Stability Board — aimed at strengthening fiat payment infrastructure in the United Arab Emirates.

Paribu continues its compliance-driven expansion

Paribu, which has been pioneering the development of the blockchain ecosystem in Turkey since 2017 and focuses on digital asset custody through its Paribu Custody brand, received approval in early August to increase the capital of its broad-authority brokerage firm, Paribu Yatırım Menkul Değerler A.Ş., to TL 530 million. With this development, the paid-in capital of Paribu Group’s Turkish subsidiaries alone reached TL 7 billion.

Having grown on its own equity since 2017, completed Turkey’s largest fintech acquisition at the end of 2025, and rolled out an update in July 2026 under the tagline “Tomorrow’s world is now broader” — aiming to bring crypto, DeFi, and equity markets together under one roof — Paribu continues its compliance-driven expansion steps across all markets it has entered.
Revolut pilots facial recognition checkout with “Pay with Smile”

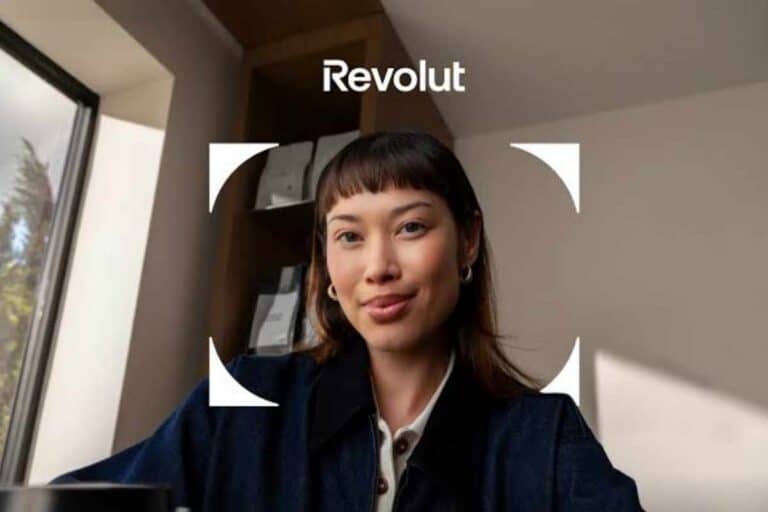
Revolut has unveiled an in-store facial recognition checkout system that allows customers to make payments with a simple glance, eliminating the need for a card or phone at the point of sale.

The feature, called Pay with Smile, is available on the Revolut Register terminal. At checkout, customers tap the Pay with Smile option on screen, triggering a face identity check that verifies the user against identity data collected during the Revolut onboarding process — similar to unlocking a smartphone or accessing a banking app. If the check is successful, an account-to-account payment is authorized instantly.

Participation is opt-in only. Customers must enable the feature in their Revolut app settings, and consent can be revoked at any time. Revolut said customers will not be enrolled by default, facial recognition data is encrypted end-to-end, and personal data will not be stored by merchants.

The technology is being piloted in London from September 24, with Revolut customers able to try it at Kiss the Hippo coffee shops in Bloomsbury, Chelsea, and Soho through September 26. Revolut said the broader rollout of the Register terminal will follow in due course.

Revolut is offering 0% processing fees on Pay with Smile transactions, a move it says is aimed at easing the financial burden on independent venues.

Alex Codina, General Manager of Merchant Payments at Revolut Business, described the feature as replacing “outdated, fragmented tills with a hyper-efficient checkout experience designed to solve consumer and merchant pain points.”

RedotPay obtains two US state lending licences

RedotPay has obtained lending licences in Idaho and Nebraska through its subsidiary Red Dot Lending (US), LLC. The approvals, announced on 23 September 2026, allow the company to offer certain lending products in both states once it launches in the US. The company has not specified a timeline for that launch.

The two licences are the first results of a wider licensing effort. RedotPay has filed more than 20 additional licence applications in other US states as part of a long-term strategy to build a compliant base ahead of its entry into the US market.

A company representative described the licences as an important step in RedotPay’s regulatory strategy. It was also added that the company’s focus is on building a compliant foundation for digital financial services in the markets where it operates.

The lending approvals follow other recent US regulatory steps, including a state-level Money Transmitter License. With lending licences now added alongside money transmission, RedotPay’s planned US offering could extend beyond payments to include credit products in the states where it holds the relevant authorisations.

Compliance credentials beyond the US

Outside the US, RedotPay’s licensed Hong Kong subsidiaries have undergone an independent review of their AML/CFT controls. A Big Four firm conducted the review, and the company says it affirmed those controls.

The company also holds several security and compliance certifications. These include ISO/IEC 27001 certification, PCI DSS compliance, and SOC 2 Type II certification. RedotPay presents these credentials, together with its recent licences, as part of its approach to operating within regulatory and compliance frameworks across its markets.

The licensing activity comes as stablecoin-powered payments are increasingly integrated with payment, card, and financial-services infrastructure. RedotPay expects spending on stablecoin-powered cards to reach an annualised USD 50 billion by 2028. The company links that projected growth to a greater need for regulatory compliance as the sector expands. For the wider ecosystem, RedotPay’s approach reflects the state-level licensing work a company has to complete before offering payment and lending services in the US. 

Ryft raises EUR 23 mln Series B to fund European and US expansion

UK-based fintech company Ryft has raised EUR 23 million in a Series B round led by Gresham House Ventures. Existing investors Pembroke VCT and Ingenii Capital also took part. The round follows a 12-month period in which Ryft tripled its processing volume. More than 6,500 businesses now use its payment system, including Epos Now, Chaiwalla, the Disasters Emergency Committee, Daytrip, and Sprive. The company plans to use the capital to expand across Europe and the US, accelerate product development, and move upmarket.

Infrastructure for multi-party payments

Founded in 2021, Ryft builds payment infrastructure for marketplaces, platforms, and multi-location businesses. Through a single integration, clients can manage seller onboarding and complex transaction flows, including recurring billing, automated split payments, and cross-border payouts. The model also allows merchants to generate additional revenue from the transactions processed on their platforms. The company is regulated by the UK’s Financial Conduct Authority (FCA).

Investors framed the round around a structural shift in commerce. Rohit Mathur, Partner at Gresham House Ventures, said payment infrastructure was originally designed for transactions between two parties, whereas commerce increasingly runs through marketplaces, franchises, and creator businesses, and in time potentially through AI agents. According to the investor, Ryft’s top-performing customers are growing their volumes on the platform by more than 100% a year.

Furthermore, Fred Ursell, Head of Investments at Pembroke Investment Managers, noted that splitting payments between multiple parties is technical and heavily regulated work, which incumbents have left underserved for around a decade. Pembroke has previously supported Ryft starting in 2024, when it first met one of the founders, Sandra Hosseini, and this round marks its third investment in the company.

Coinbase opens IPO allocations to US retail traders

Coinbase has launched IPO allocations for eligible US retail customers via Coinbase Capital Markets, starting with Oura’s offering.

Customers can request shares at the offer price before open-market trading begins. Oura’s IPO, scheduled to begin on September 21, 2026, the same week the announcement was made, is the first deal available.

The launch extends the company’s activity into primary financial markets and is part of its ‘Everything Exchange’ strategy. Under this approach, Coinbase aims to give US customers exposure to companies before their shares reach public exchanges, rather than only after listing.

How the allocation process works

Requests are managed in the Coinbase app, where a new IPOs page lists active deals. Customers select a deal page and fund their account to cover the cost of the shares they want. Once the expected price range for the offering is public, they can submit a ‘Conditional Offer to Buy’.

Offers can be edited or cancelled throughout the open period. However, if the price changes beyond a set limit, customers must resubmit their request to stay in the running for an allocation.

After the order book closes, Coinbase allocates available shares using what it describes as an established methodology and books them into customer accounts at the IPO price. Final allocations depend on underwriter supply and total customer demand, so requests may be filled in full, in part, or not at all. Allocated shares become tradable on Coinbase as soon as public market trading in the stock begins.

Allocation rules and holding periods

Coinbase has designed its allocation algorithm to prioritise investors who intend to hold their shares over the long term. Customers who sell IPO shares within the first 30 days may be barred from IPO participation for the following 60 days. Those who repeat this behaviour may receive smaller and less frequent allocations than investors who hold their shares for longer.

Because the shares available depend on underwriter supply, the algorithm determines how that limited pool is shared among customers. Holding behaviour is one of the factors that shapes each customer’s future access.

Reap and Visa expand stablecoin card programmes to over 100 markets

Reap has partnered with Visa to launch stablecoin-linked Visa credit card programmes across more than 100 markets globally. Programmes will be rolled out in compliance with local regulations. According to the announcement, Reap will become the first fintech in Asia to partner with Visa on global stablecoin credit card issuing at scale.

Reap’s infrastructure covers card network authorisation, card processing, compliance frameworks, and operations. This allows partner companies to launch and scale card programmes without building these functions in-house, leaving their teams to concentrate on product development and growth.

Card programme capabilities and use cases

Through Reap’s infrastructure, fintechs, businesses, and platforms can offer credit card programmes in which stablecoins are used to fund and manage spending. Partners can use stablecoins as collateral, allow cardholders to repay balances in stablecoins, and support cross-border corporate spending with compliance and programme management built in. Cards issued under the programmes can be used at more than 175 million Visa-accepting merchant locations worldwide.

The companies outlined three main use cases. The first is corporate treasury and cross-border spend, where businesses fund credit cards with stablecoins to manage international expenses. The second is global payouts and vendor spend, where platforms support business payments and payouts through a card experience, with stablecoins powering the settlement flows. The third is Embedded Finance for B2B platforms, which can launch branded card programmes that integrate stablecoin funding and repayment into their existing products.

Market context

The collaboration comes as stablecoin-linked card programmes gain traction. Data from Artemis Research cited in the announcement shows the segment growing at a 106% compound annual growth rate, compared with 5% for P2P payments. Visa reports a USD 20 billion annual run rate in global stablecoin settlement volume, up 15-fold year on year. More than 160 stablecoin card programmes operate on its network globally.

Warning for online shoppers against “IBAN” and “Fake Payment Link” scams

Experts are warning consumers who shop on e-commerce platforms against those who, under various pretexts related to their orders, redirect them to make payments outside the platform. Consumers shopping on e-commerce platforms are increasingly being directed to make payments outside the platform under various pretexts related to their orders. This situation is causing financial harm to a number of consumers.

Experts are warning consumers against requests to send money via IBAN, citing pretexts such as “there is a problem with your order,” “the product price was entered incorrectly,” or “you need to pay the price difference.”

Muharrem Baki, Chair of the Cybersecurity Commission of the Consumer Confederation, told an AA correspondent that one of the fraud methods recently encountered by online shoppers involves manipulating the order process to get consumers to send money via IBAN.

Recalling that payments via IBAN were previously common in purchases made through social media platforms, Baki said: “Consumers’ habit of shopping on social media platforms and sending payments via IBAN gave fraudsters the opportunity to exploit this behavior to their advantage. This type of fraud initially started simply as a method of taking money without sending any product.”

Baki noted that fraudsters today are able to use consumers’ actual purchase and order information to demand money through various methods, and added: “The real goal behind pretexts such as ‘there is a problem with your order,’ ‘the product price was entered incorrectly,’ or ‘you need to pay the difference for your order to proceed’ is to get consumers to leave the platform and send money directly to their accounts. Why do citizens fall for this and become victims? Because trust is established — you think the platform actually knows about your purchase. However, if malicious individuals gain access to your information and personal

Go.AI raises $85m Series A for on-prem AI push

Go.AI™, a Chicago-based provider of on-premises, examiner-ready AI infrastructure, built for banks, healthcare providers and other regulated organisations, has closed an $85m Series A funding round.

The financing was led by Updata Partners, with existing backers GFT Ventures and LAUNCH also taking part, lifting Go.AI’s total capital raised to date to $90m.

The raise comes shortly after the company’s rebrand from Go Abacus and follows a year of momentum that began with the launch of The Go1™, described as the first on-prem AI hardware and software solution built specifically for regulated organisations.

Go.AI has since expanded to more than 200 customers, with annual recurring revenue climbing over eightfold year on year while the business remains profitable. Customers are now running on-premises AI deployments that together handle upwards of 12.5 million queries daily, with the heaviest demand coming from financial services, healthcare, aerospace and defence, and manufacturing firms.

Go.AI provides regulated institutions with private AI infrastructure that operates inside their own secure environments, combining software and hardware so that sensitive data never has to leave the customer’s systems. The platform is designed around the auditability and governance standards these sectors are held to, letting organisations put AI into production rather than treat it as an experiment, and is offered for a fixed fee rather than usage-based pricing.

The new funding will go towards growing Go.AI’s engineering headcount, speeding up development of its Go.OS software and hardware line, and expanding go-to-market efforts as the company looks to move beyond its core regulated-industry base into a wider group of compliance-focused organisations.

Alongside this, Go.AI plans to keep growing its team while putting more resources into training and client advisory work aimed at improving customers’ understanding of secure, on-premises AI. That includes a forthcoming company podcast series and wider marketing activity intended to push back against fear-based narratives about AI adoption and show organisations how to bring the technology in with confidence.

Go.AI co-founder and CEO David Moscatelli said, “When Lisa Gillespie and I cofounded the company, we were two people with a big idea. Today we have over 50 team members, and the company we’ve built is doing exactly what we said it would do for the institutions that trust us most.

“This funding lets us keep building at that pace, but the thing I’m most proud of isn’t the growth number, it’s the education. AI doesn’t have to be something people fear or don’t understand. Done right, it works alongside the people who use it. That’s what this round lets us prove, at scale.”

Updata Partners general partner Carter Griffin said, “Go.AI built the AI stack that regulated institutions can actually deploy: software and hardware that live inside the customer’s secure environment with no proprietary data going to a third party. All of this at a fixed fee with no per-token surprise costs.

“Go.AI’s combination of explosive growth and profitability is exactly what we look for at Updata. We are thrilled to partner with David, Lisa, and the entire Go.AI team.”

Unlimit migrates global accounts business to Stable.com

Unlimit, a global financial infrastructure company, has started moving Unlimit Accounts onto Stable.com, its full-service financial platform. The migration consolidates Unlimit’s existing global accounts business under Stable.com, which the company positions as a unified platform combining conventional payment infrastructure with digital asset capabilities.

Platform structure and reach

Stable.com is built around a single global account that carries local payment details, allowing users to hold multi-currency balances alongside bank transfers, card issuance, and treasury management tools. The platform is powered by Unlimit’s proprietary payment network and provides access to payment systems across more than 180 countries, with local payout capability in more than 150 currencies. This structure is intended to let businesses and individuals manage cross-border payments through one account rather than maintaining separate relationships for each currency or market.

Beyond traditional payment rails, Stable.com incorporates access to tokenised assets and non-custodial decentralised finance (DeFi) across five blockchain networks: Ethereum, Solana, BNB Smart Chain, Tron, and Polygon. Users can connect self-custody wallets to the platform and initiate bank transfers in their own names using stablecoins they already hold, without needing to first move those assets into a custodial account. This design keeps custody of digital assets with the user while still enabling their conversion into traditional payment flows.

Strategic rationale

The migration reflects a broader industry trend of payment providers attempting to bridge fiat and digital-asset infrastructure within a single interface, rather than requiring separate systems for each. According to Kirill Eves, Founder and CEO of Unlimit, the underlying rationale is that users increasingly expect money to move across currencies, accounts, and blockchain networks without needing to manage the technical infrastructure separately. Unlimit frames Stable.com as an attempt to remove that distinction by offering one platform for managing funds regardless of the currency, asset type, or network involved.

Six global banks publish principles for trusted agentic commerce

ING Group, NatWest Group, ASB Bank, Bank of America,, Capital One, and Commonwealth Bank of Australia have jointly published a shared set of principles intended to support the development of trusted agentic commerce. The paper is aimed at establishing a framework for a future in which AI agents play a greater role in how consumers and businesses select and pay for products and services.

The six institutions position themselves at the centre of the payments ecosystem, connecting consumers, businesses, and merchants across a high volume of daily transactions. As agentic commerce develops, the participating banks state that customers and merchants should retain choice, control, and flexibility over how payments are made and received, while transactions remain safe and secure.

Five focus areas

The principles address five areas: transparency, safety, privacy and data, choice, and interoperability. Together, these are intended to provide a foundation for further discussion on how agentic commerce should develop across the industry, rather than a finished standard.

Representatives from the participating banks described agentic commerce as a development with the potential to reshape how customers shop and pay, while stressing that trust, identity verification, fraud prevention, and liability management need to be addressed as AI agents take on a greater role in transactions. Several representatives also linked the initiative to broader payments modernisation efforts already underway in their respective markets, including in New Zealand and the UK.

Next steps and wider engagement

The publication builds on an ongoing industry conversation rather than concluding it. The consortium has invited other banks and institutions across the payments ecosystem to engage with the principles, contribute perspectives, and collaborate on a blueprint for applying them in practice. According to notes accompanying the announcement, the group’s next step is to publish a further paper detailing how the principles can be implemented, with continued engagement expected from customers, industry participants, and other stakeholders as the work progresses.