Home Blog Page 8

Paribu becomes Turkey’s launch partner for Arc

Paribu has announced that it is among the launch partners in Turkey for Arc, the open Layer-1 network developed by Circle, the issuer of USDC, which went live on its mainnet today. As part of the partnership, USDC deposits and withdrawals via Arc on Paribu are supported from the very first day of the blockchain’s mainnet launch.

Paribu, which has been pioneering the development of the blockchain ecosystem in Turkey since 2017, is joining as a launch partner for Arc, the open Layer-1 blockchain network developed by Circle, the issuer of USDC — the second-largest stablecoin by market capitalization. Under the partnership, USDC deposits and withdrawals via Arc on Paribu are supported from the blockchain’s first day on mainnet.

“The economic operating system of the internet”

Arc describes itself as the economic operating system of the internet, positioning itself as an open, EVM-compatible Layer-1 platform built for global financial markets, real-time money movement, and economic activity conducted by AI agents. On Arc, transaction fees are paid in stablecoins starting with USDC, meaning users do not need to hold a second asset to cover fees. According to data shared by Circle, tests conducted with the participation of more than 100 ecosystem and institutional developers — focused on stablecoin payments, tokenized asset issuance, global foreign exchange transactions, and institutional on-chain markets — saw average transaction costs remain below $0.01. Arc’s security is provided by a validator network composed of financial institutions across different geographies, with participants including BlackRock, Mastercard, Visa, Intercontinental Exchange, and Standard Chartered.

USDC deposits and withdrawals via Arc now live on Paribu

Having joined the Arc launch as a Day 1 Launch Partner, Paribu began supporting USDC deposits and withdrawals via Arc from the blockchain’s first day on mainnet. Paribu’s Day 1 support also means that any asset issued on Arc is accessible through Paribu DeFi simultaneously with the rest of the world.

Paribu Custody supports Arc from day one

Paribu Custody, the Paribu subsidiary and Turkey’s first and only digital asset custody service provider operating on its own proprietary technology, also announced that it is among the institutional crypto asset custody providers supporting Arc from day one. Institutional users can now store their Arc-based assets with the assurance of ColdShield®, which combines HSM, MPC, and Secure Enclave technologies. Paribu Custody, which already supports more than 1,000 tokens across over 90 networks, is extending its network coverage with the addition of Arc.

The beginning of a long-term potential

Arc’s scope extends well beyond stablecoin transfers, encompassing capabilities such as local currency-denominated stablecoins, tokenized assets, and programmable Bitcoin. At launch, Arc has also activated features including lending and borrowing, on-chain foreign exchange, payments, and tokenized asset markets. These broad capabilities align with Paribu’s approach of making new financial instruments accessible through intuitive experiences — not only in Turkey but also across the Middle East and North Africa through CoinMENA. For Paribu, which is targeting broader emerging markets, this collaboration opens the door to potential opportunities across different geographies.
Mastercard Turkey earns Great Place To Work certification again

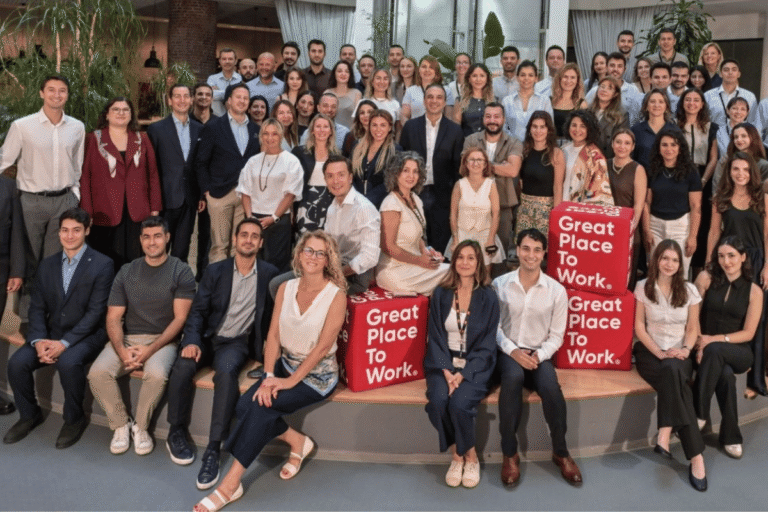
Mastercard Turkey has once again earned the Great Place To Work-Certified designation from Great Place To Work, the global authority on employee experience and workplace culture.

According to the Trust Index employee survey, 91% of Mastercard Turkey employees described the company as a great place to work overall. The results painted a strong picture across categories including safe working environment, fairness, inclusivity, and employee pride in their organization.

94% of survey participants said they are proud to tell others they work at Mastercard, while 97% stated that everyone is treated fairly regardless of nationality or background. 96% of employees said the company offers a fair and inclusive working environment, and 99% confirmed it provides a safe one.

Mastercard Turkey, which was also recognized as a Great Place To Work in 2023, was additionally named among the top three employers in the 100–499 employee category on the Best Workplaces in Financial Services & Insurance 2026 list. The two achievements together reflect the company’s approach of placing employee experience at the core of its long-term organizational culture.

“The real owners of this achievement are our colleagues”

Mastercard Turkey and Azerbaijan General Manager Onur Faydacı said: “At Mastercard, we believe that diverse perspectives strengthen innovation, and that trust and mutual respect form the foundation of sustainable success. Creating a culture where our colleagues feel valued, safe, and a sense of belonging — and where they can freely share their ideas — is one of our top priorities. The fact that this certification is based directly on our employees’ own assessments makes it all the more meaningful to us. We are very pleased to see the strong organizational culture we have built together in Turkey recognized by an independent body. I would like to thank all my colleagues, the true owners of this achievement.”

Mastercard aims to provide employees with opportunities to learn, grow, and contribute through diverse perspectives, building a work environment where everyone feels supported, connected to one another, and able to fully realize their potential.

The Great Place To Work certification is based on the Trust Index employee survey, which measures workplace experience across areas such as pride in the organization and relationships among colleagues. The certification is awarded to organizations that meet the global standard for a positive workplace culture, based entirely on direct employee feedback.

Paywall shares details on its payment infrastructure anomaly detection system

Paywall, known for its innovative infrastructure solutions in financial technologies, has shared details on System Anomaly Detection, a tool designed to identify hidden and dispersed anomalies in multi-provider payment infrastructures at an early stage. The solution analyzes normal behavior profiles built from each customer’s own payment data and, when needed, draws on Paywall’s system standards to help determine which bank, provider, card group, or transaction flow is causing the issue, reducing potential revenue and operational losses.

Brief or partial disruptions in payment infrastructure can lead to revenue loss, lower conversion rates, increased customer complaints, and rising operational costs for businesses. Since problems do not always manifest as full system outages, performance drops in specific banks, payment institutions, card groups, or transaction types often go unnoticed until it is too late. Early detection of anomalies at the customer and transaction level is therefore critical for revenue, operational efficiency, customer experience, and brand trust. System Anomaly Detection can identify a wide range of irregularities, from unexpected drops in payment success rates to failure concentrations in specific banks, payment institutions, card groups, installment options, or transaction types.

System operates within each customer’s own payment data

System Anomaly Detection works primarily within the scope of each customer’s own payment data. It analyzes indicators such as transaction volume, payment success rate, error codes, response times, timeout rates, and provider performance to build a customer-specific normal behavior profile. Since every business differs in sector, transaction volume, peak hours, campaign periods, and payment providers, the system applies each business’s own dynamics rather than fixed thresholds across all customers. A drop in transaction volume at a given hour may be entirely normal for one customer while signaling a critical anomaly for another.

Preventing potential revenue and operational losses

In addition to customer-specific data, the product can also draw on Paywall’s system anomaly standards, which cover general risk indicators such as critical drops in payment success rates, sudden spikes in error codes, unusual response times, and connection timeouts. The customer-specific behavior profile and Paywall’s system standards can be used separately or together depending on need, creating a two-layered detection mechanism that accounts for both a business’s unique payment patterns and conditions that are broadly considered critical in payment systems. Beyond success rate drops and failure concentrations, the system also monitors rejection and connection errors, increases in response times, unusual shifts in transaction volume, synchronization issues between payment status and system notifications, rises in retry and alternative provider usage, and commission and reconciliation discrepancies. The goal is to surface local issues that might otherwise be invisible in overall performance metrics, catching them early at the provider and transaction segment level to prevent revenue and operational losses.

“We are moving payment operations from reactive to proactive”

System Anomaly Detection works in integration with Paywall’s payment orchestration layer, continuously analyzing transaction flows across different banks and payment institutions. When a performance drop is detected at a provider, the resulting anomaly signal can, depending on defined rules, support PayRoute in redirecting traffic to a healthier provider or trigger PayJump’s alternative payment recovery flows. When used alongside Fraud LLM, it helps make faster sense of technical outages, provider performance degradation, shifts in customer behavior, and suspicious transaction activity.

Paywall CEO Arif Ferah, noting that every transaction should be routed to the right provider at the right cost with the highest possible chance of success, said: “Reacting after a problem appears is no longer enough. With System Anomaly Detection, we are moving payment operations from a reactive structure to a proactive, data-driven one. We offer a flexible approach that understands each business’s unique payment behavior from its own data and draws on Paywall’s system standards when needed. Our vision is to build an increasingly intelligent, self-optimizing payment ecosystem — one that detects anomalies early, makes their impact visible, and enables faster action through Paywall’s orchestration capabilities.”

Gemini secures Singapore MPI licence for crypto services

Gemini has received a Major Payment Institution licence from the Monetary Authority of Singapore. According to the announcement, the licence was given to Gemini Digital Payments Singapore, the company’s locally incorporated entity.

The MAS Financial Institutions Directory lists Gemini Digital Payments Singapore as authorised to provide digital payment token services and cross-border money transfer services. Holders of an MPI licence can offer these regulated payment services without the transaction-volume limits applied to standard payment institutions. MAS subjects major payment institutions to more comprehensive regulatory requirements, citing the greater risks associated with the scale of their operations.

Company presence and licensing timeline

Gemini has operated in Singapore since 2020, offering spot crypto trading, digital asset custody, and over-the-counter services to retail and institutional clients. Company representatives have described Singapore as a strategic hub for the exchange’s regional business.

MAS granted in-principle approval for Gemini’s application in October 2024, as previously reported. In April 2025, Gemini transitioned its Singapore customer base from Gemini Trust Company, which had operated under a regulatory exemption, to Gemini Digital Payments Singapore, the entity through which it continued working toward full authorisation.

Implications for the region’s digital asset sector

The MPI licence places Gemini among the digital asset firms that have secured this authorisation category in Singapore, a jurisdiction that has developed a structured regulatory framework for digital payment token services over recent years. Full MPI status allows Gemini to expand its regulated service offering in the country without the volume constraints attached to a standard payment institution licence, providing a basis for continued operations serving both retail and institutional clients in the region. The approval also reflects the multi-year timeline typically associated with moving from in-principle approval to full licensing under Singapore’s payment services regime.

India’s NPCI launches NFC-based UPI Tap & Pay for POS payments

National Payments Corporation of India (NPCI) has launched UPI Tap & Pay, enabling faster in-store payments via smartphones and POS terminals. UPI Tap & Pay is built for use with NFC-enabled smartphones and NFC-enabled POS terminals. To initiate a payment, a user unlocks their phone and taps it against the POS device, without needing to open a separate application screen for each transaction step. The feature does not require an active mobile internet connection since the transaction is processed using the POS terminal’s own connectivity.

The capability supports payments drawn from multiple UPI-linked account types, including RuPay Credit Card on UPI. Transactions of up to USD 52.3 do not require a UPI PIN, while payments above that threshold require the user to enter their PIN directly on the POS terminal.

This tiered authentication approach mirrors contactless card payment structures already in use across other markets, positioning UPI Tap & Pay as an extension of India’s A2A payment infrastructure into the contactless POS environment dominated by card networks.

MyUPI adds AI-based support tools

Alongside Tap & Pay, NPCI also introduced MyUPI, described as an AI-powered platform designed on its small language model, FiMI. The platform expands the existing UPI Help service, focusing on user support across UPI applications and banks.

In addition, MyUPI offers a view of the user’s UPI transactions and AutoPay mandates spanning multiple banks and UPI applications. It also introduces a Safety Switch, which lets users request that UPI debit transactions be declined if they suspect their account has been compromised. Furthermore, the UPI Number Delink feature allows users to remove their mobile number from receiving UPI payments.

Additional functions include payee context-based information, automated real-time chargeback processing for eligible transactions, and a transaction replay tool that allows users to repeat past payments through any UPI app. The platform will offer round-the-clock multilingual support alongside self-service tools across the UPI infrastructure.

Klarna launches call verification tool in the Nordics

Klarna has launched an in-app call verification tool across the Nordics to help customers identify genuine calls. Sweden-based Klarna has announced that its in-app Call Status Detection feature is now live across the Nordic region, giving customers a way to check whether a call claiming to be from the company is genuine. The tool is designed to help users identify impersonation attempts during live phone calls, adding to the company’s existing suite of anti-fraud measures.

How the feature works

Call Status Detection integrates with the Klarna app to provide real-time verification during phone calls. When a customer receives a call from someone claiming to represent Klarna, they can open the app and check a banner displayed at the top of the screen. A green banner confirms the call has been verified as genuine, while an amber banner indicates Klarna cannot verify the call, signalling that the customer should end it.

The feature extends the Klarna Inbox, a tool previously introduced to let customers verify written communications such as emails, text messages, and letters claiming to originate from the company. Together, the two features are intended to give customers a consistent way to check the authenticity of both written and verbal contact points.

Call Status Detection will be enabled by default for iOS users in Sweden, Norway, Finland, and Denmark, with the company stating that additional regions will follow. Android users will need to activate the feature manually through their Klarna app settings.

Industry context

Impersonation fraud targeting banks and payment providers over the phone has become one of the faster-growing categories of financial crime, partly because caller ID information can be spoofed with relative ease, allowing fraudsters to appear as though they are calling from a legitimate institution. According to the European Central Bank, fraudsters steal more than EUR four billion annually across Europe.

Woody Malouf, Klarna‘s Head of Financial Crime, said scammers are becoming more sophisticated and that the company aims to help consumers respond, noting that Call Status Detection is intended to work alongside the Inbox feature to give customers a quick way to verify contact and protect their funds.

Bybit to launch European super-app with stocks, derivatives

Bybit has secured an electronic money institution licence in Austria and is preparing a European super-app. According to CoinDesk, the EMI licence adds to the Markets in Crypto-Assets (MiCA) licence Bybit already holds in Austria, which gives it access across the EU. The company is also close to obtaining a Markets in Financial Instruments Directive (MiFID) licence, expected within about two months.

Building a regulated, multi-licence offering

CEO Ben Zhou said the combination of the three licences would allow Bybit to operate in a manner comparable to Revolut, which holds a full banking licence in the EU and the UK and serves a similarly sized user base. He noted that a MiCA licence alone is not sufficient to build a profitable business in the region, citing compliance costs and competition from firms offering a broader range of financial products. In addition, Bybit has operated under its MiCA licence for around a year without turning a profit, he said, adding that the EU market requires multiple licences to compete effectively against established financial apps.

The EMI licence will enable Bybit users to hold individual accounts with an International Bank Account Number (IBAN), receive salary payments, pay bills, and carry out local transfers, alongside existing crypto and stablecoin functionality. This positions the planned app as a single access point for both traditional payment services and digital asset trading.

Derivatives and tokenised equities on the roadmap

Once the MiFID licence is granted, Bybit intends to offer regulated derivatives, including contracts for difference on commodities such as gold, silver, and oil. The licence would also support connections to brokers such as Alpaca or Saxo Bank, enabling clients to hold shares in companies including Apple and Tesla directly within their accounts.

For tokenised equities, Bybit will continue its existing partnership with Kraken’s xStocks product rather than building the capability independently. Zhou said Bybit Global remains xStocks’ largest distribution partner and that the relationship with Kraken will continue as the super-app develops.

Thunes launches cross-border payouts across six new Middle East markets

Thunes, the Smart Superhighway to move money around the world, today announced a major expansion of its Direct Global Network across the Middle East. The expansion introduces new payout services into six key markets: the Kingdom of Bahrain, Lebanon, the Sultanate of Oman, South Yemen, Syria and the United Arab Emirates (UAE).

This move significantly enhances Thunes’ cross-border infrastructure in the region, delivering faster, highly transparent payment solutions for Members of Thunes’ Direct Global Network. Members can now process payouts to millions of bank accounts, mobile wallets, and cash pickup locations in local currencies throughout the region, either through direct API integration with Thunes or by leveraging existing Swift connectivity.

The regional rollout builds on Thunes’ expansion of real-time payments across the Kingdom of Saudi Arabia in September 2025 and targets diverse economic needs across the Middle East:

  • Powering Digital Economies: In Bahrain, where the non-oil sector contributed 85% of real GDP in 2025, Thunes supports direct bank payouts aligned with the nation’s National Digital Economy Strategy. In Oman, bank account payouts support the digital transformation goals of Oman Vision 2040 alongside projected GDP growth of 4% in 2026.
  • Fueling Enterprise and Consumer Growth: In the UAE, a primary regional payments hub driven by the National Payment Systems Strategy (NPSS), Thunes now supports bank account payouts for both consumers and enterprises.
  • Delivering Vital Remittance Lifelines: In markets relying on remittance flows for economic resilience and recovery, Thunes provides critical access points:
  • – Lebanon: Supporting mobile wallet payouts in a market receiving roughly $7 billion per year in remittances.
    – South Yemen: Enabling bank and cash pickup payouts where remittances represent over 38% of its total GDP, ranking among the top three most remittance-dependent nations globally.
    – Syria: Introducing payouts to cash pickup locations, providing reliable financial access amid broader efforts to rebuild the local banking system.

Chloé Mayenobe, Deputy CEO at Thunes, said: “Launching new payout capabilities across the Middle East unlocks significant value for our Members and their end-users. These markets are deeply committed to digital innovation and financial inclusion. Thunes is proud to provide the infrastructure that empowers businesses and individuals to participate seamlessly in international commerce and the broader global economy.”

With this expansion, Thunes reinforces its position as a leading provider of global money movement. The solutions leverage Thunes’ in-house SmartX Treasury System for AI-driven forecasting and real-time liquidity management, and its Fortress Compliance Platform, which benefits from over 50 licences worldwide, ensuring that every payment is executed with the highest levels of security, compliance and operational efficiency.

Mastercard launches Wallet Pay to scale digital wallets worldwide

Digital wallets have rapidly evolved into robust, multi-service platforms, now serving over 4.3 billion users worldwide. With global usage set to top 6 billion by 2030, Mastercard is introducing Mastercard Wallet Pay, a global portfolio of solutions designed to foster interoperability and innovation for digital wallets across contactless (NFC), QR codes and online digital payments.

Harnessing the industry’s most advanced capabilities, Mastercard Wallet Pay solutions empower wallet providers to deliver frictionless experiences — from everyday spending to cross-border transfers – meeting the demands of a rapidly expanding digital economy.

Through collaborations with leading digital payment service providers including Alipay+ — the global wallet gateway of Ant International that supports its partner wallets such as AlipayHK, Clip, GCash, KakaoPay, TNG eWallet and TrueMoney — together with Axian, CRED, DaviPlata, Mercado Pago, MTN and TenPay Global, Mastercard Wallet Pay expands access to essential financial tools and enables acceptance at hundreds of millions of acceptance locations and digital access points worldwide, ensuring that people everywhere can participate in the digital economy.

Wallet Pay reinforces Mastercard’s commitment to powering stored value digital wallets across its global payments network. Leading wallet providers are choosing Mastercard for its global acceptance and digital access points, while providers such as Alipay+ — which connects more than 50 e-wallets and banking apps as well as over 10 national payment schemes worldwide — are helping enable their wallet partners to connect to Mastercard Wallet Pay at scale.

A portfolio built for possibility

With technologies like cloud-based payments and Mastercard’s global acceptance network, wallet providers can leverage Mastercard Wallet Pay and bring new use cases to life without significant changes to their infrastructure.

Whether travelers are linking their cards to local wallets, businesses are moving money instantly or communities are accessing financial tools for the first time, Wallet Pay solutions are engineered for inclusion, innovation and scale:

  • Interoperability: Enables smooth connections between wallets across borders, platforms and payment types
  • Secure issuing: Supports providers in launching their own credit, debit or prepaid card programs, unlocking new revenue streams and deepening customer engagement.
  • Unified digital and e-commerce experiences: Allows merchants to accept payments from cards and wallets in person and online, enabling more than 3.7 billion Mastercard credentials to connect to digital wallets – driving transaction growth across channels.
  • Accelerated money movement: Facilitates fast transfers between cards, wallets or accounts across 200-plus countries and territories and 150 currencies.
  • Expanded access: Delivers low-cost financial tools to underbanked and unbanked consumers and supports digital inclusion in emerging regions. 

“Wallets are gateways to the digital economy and launchpads for broader financial services,” said Jorn Lambert, chief product officer at Mastercard. “Through our Wallet Pay solutions, we’re helping payment providers to enhance the interoperability and user experience of their services, underpinned by trust, scale and convenience for the people and businesses they serve.”

“Consumers and merchants don’t think about the complexity behind payments. They simply want to pay and get paid using the payment experiences they already know and trust, whether they’re shopping at home or abroad,” said Joyce Bo, executive vice president, Core Payments, Asia Pacific, Mastercard. “The first chapter of digital wallets was adoption. The next chapter is interoperability at scale. As wallet ecosystems mature, the challenge is extending their reach across more merchants, use cases and borders. Mastercard Wallet Pay helps wallet providers expand what they can offer, from cross-border payments to card issuing, without having to build all of that connectivity themselves.”

Mastercard Wallet Pay builds upon the company’s longstanding commitment to driving financial inclusion. This includes the recently announced Global Financial Health Coalition, which brings together leading digital wallet providers to help close the gap between access and true financial health.

Saudi fintech Tabby raises $233 million at $6.5 billion valuation led by Blue Pool Capital

Saudi-based fintech firm Tabby has raised $233 million in equity funding, valuing the company at $6.5 billion as it expands its financial services offering.

The new capital will support Tabby’s next phase of growth as it expands beyond its buy now, pay later offering into broader financial services in the Kingdom and the UAE.

Blue Pool Capital led the round, with existing shareholders HSG, Wellington Management and Arbor Ventures also participating, according to a statement.

Tabby was founded in the UAE in 2019 and relocated its headquarters to Saudi Arabia in 2023.

That year, it became the Middle East and North Africa’s first fintech unicorn after a funding round valued the company at more than $1.5 billion.

Tabby has been profitable since 2023 and now processes more than $18 billion in annualized transaction volume across 25 million registered users and 70,000 business partners.

Saudi fintech sector grows

The expansion comes as the Kingdom’s fintech sector continues to grow under the National Fintech Strategy. The number of companies operating in the sector reached 281 in August 2025, up from 82 in 2022, while the strategy targets 525 by 2030.

“We began with a button at an online checkout to help people spread costs over time. Everything since, every product and every licence, has come back to the same idea: people deserve more from their money. This round means we can build further on that, without changing how we think about growth or discipline,” Hosam Arab, CEO and co-founder of Tabby, said.

Chief Investment Officer at Blue Pool Capital Christopher Wu said: “Tabby has demonstrated an impressive ability to innovate for their customers, evolving beyond payments to become the trusted platform for millions of people managing, spending and growing their money across the region.

“We are proud of our partnership with Tabby over the past three years, and we are excited to continue supporting the impressive growth of the company with this financing.”

New licences broaden offering

The funding round also includes a liquidity option for employees. Since 2023, Tabby has conducted share tenders that have enabled more than $100 million in employee share sales, allowing current and former employees to realize part of the value they helped create.

Over the past year, Tabby has obtained licenses to broaden its financial services for consumers and businesses.

The Saudi Central Bank has granted the company consumer and small and medium-sized enterprise financing licenses, enabling it to provide larger, longer-term financing to consumers and working capital solutions for businesses.

Tabby also acquired Tweeq, a SAMA-licensed digital wallet, expanding its capabilities to include accounts, cards and money transfers.

In the UAE, Tabby obtained a Stored Value Facilities licence from the Central Bank of the UAE, enabling it to launch Tabby Cash as an alternative to a debit account without account or card fees.

The service offers cashback on card purchases and allows customers to make local and international money transfers.